How often should you remodel? See typical timelines for kitchens, baths and exteriors, warning signs to watch for, and how North Georgia weather plays a role.
Explore 8 wellness-focused 2026 remodeling trends for North Georgia homes, from natural light and cleaner air to spa baths, flex rooms and outdoor living.
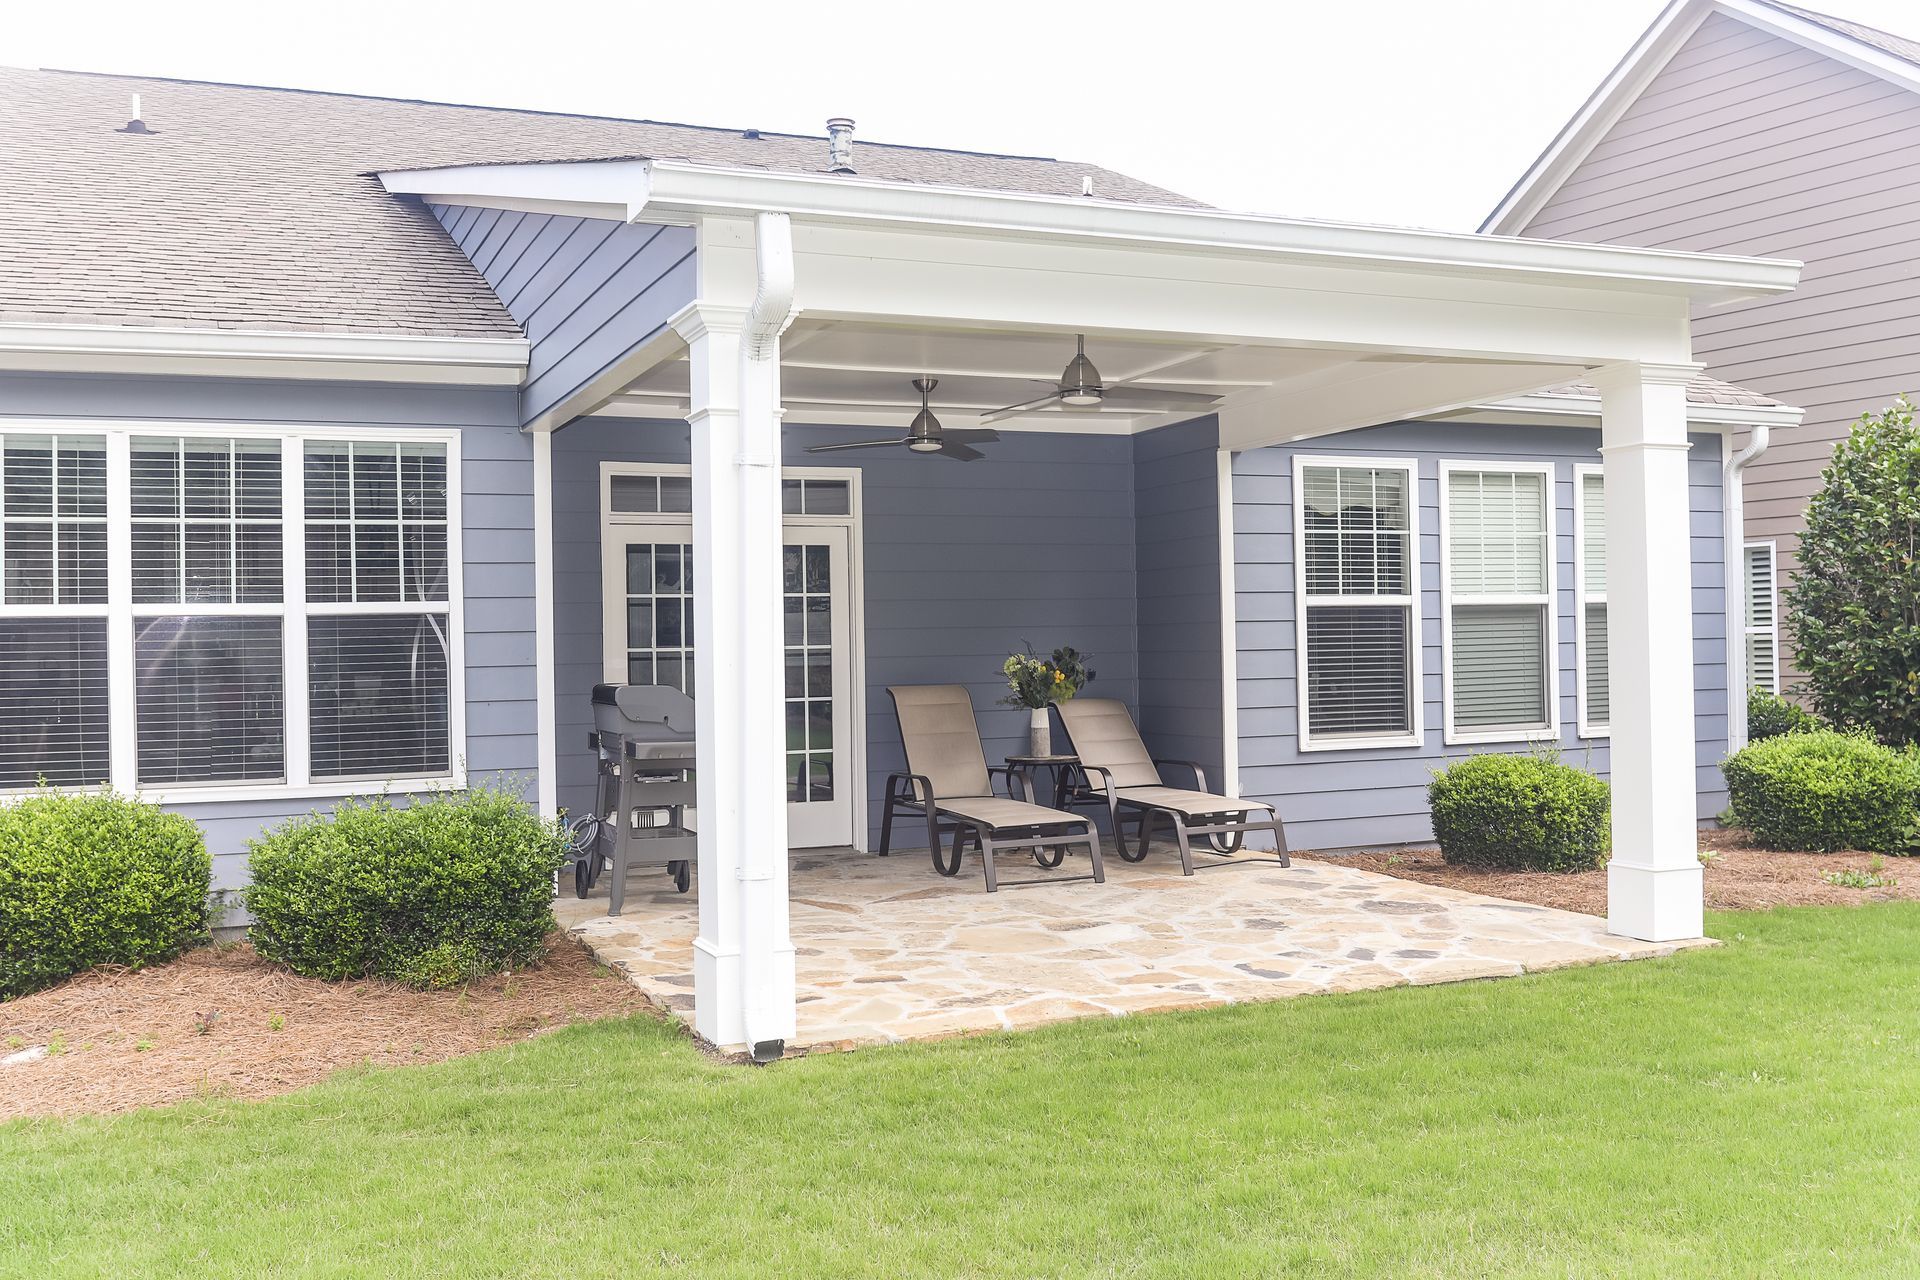
Outdoor wellness spaces are a top 2026 home trend. Explore biophilic design, purpose driven zones, spa features and year-round comfort for North Georgia homes.
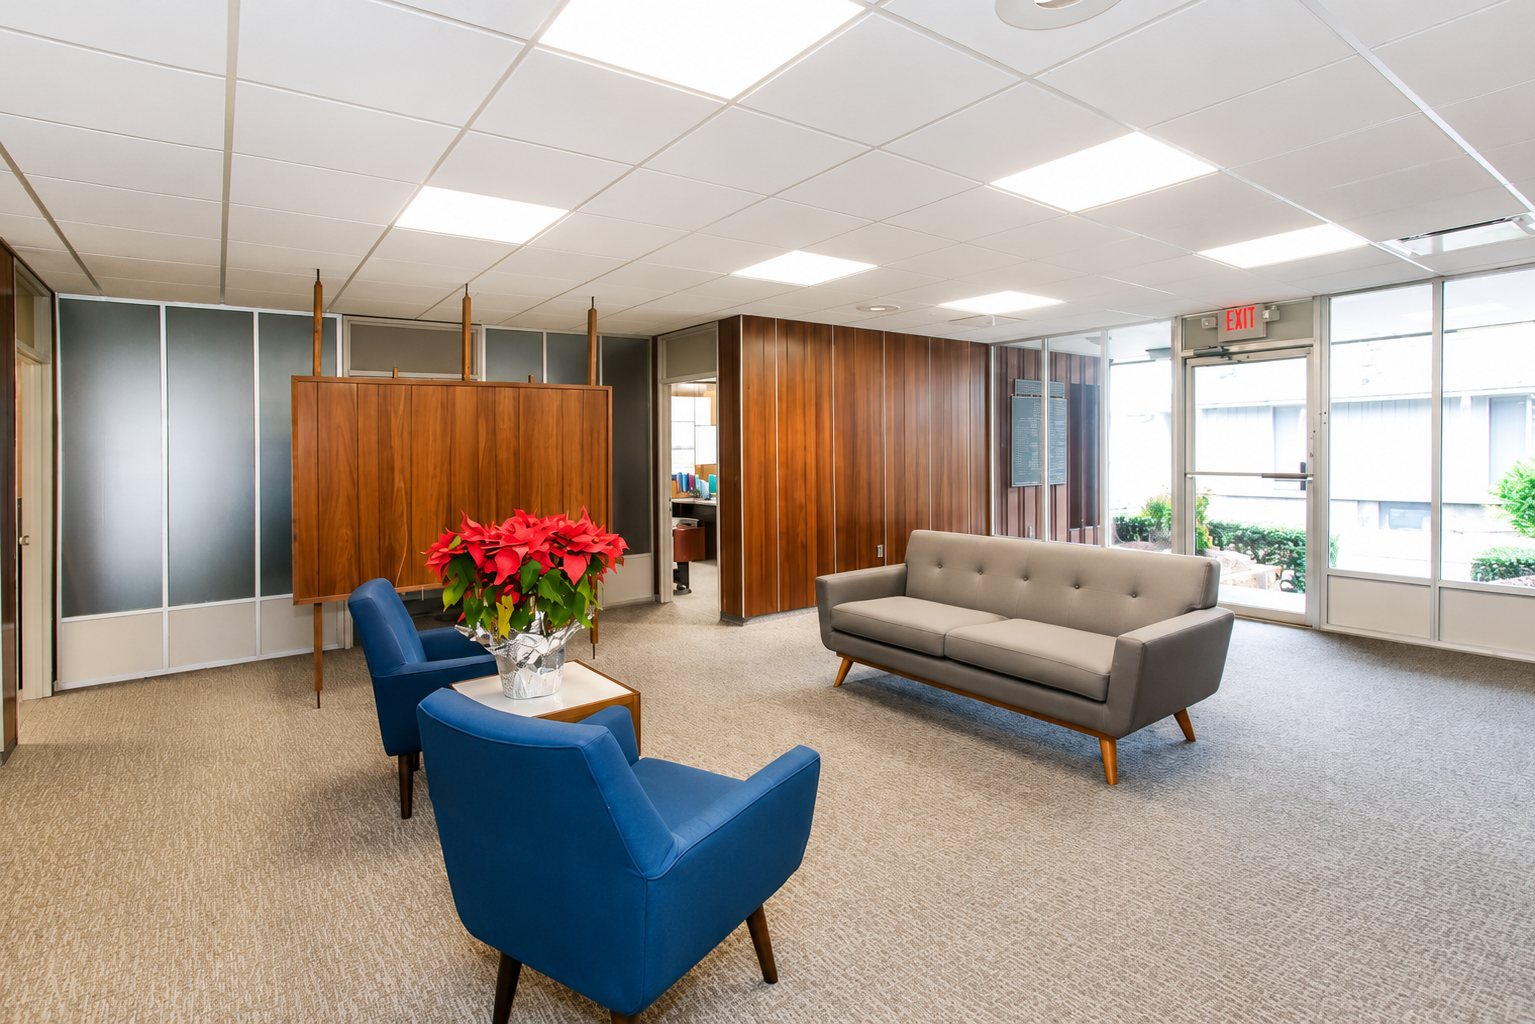
Commercial remodeling for Gainesville and Hall County businesses. Improve layout, flow and finishes in offices, retail, medical and restaurant spaces.
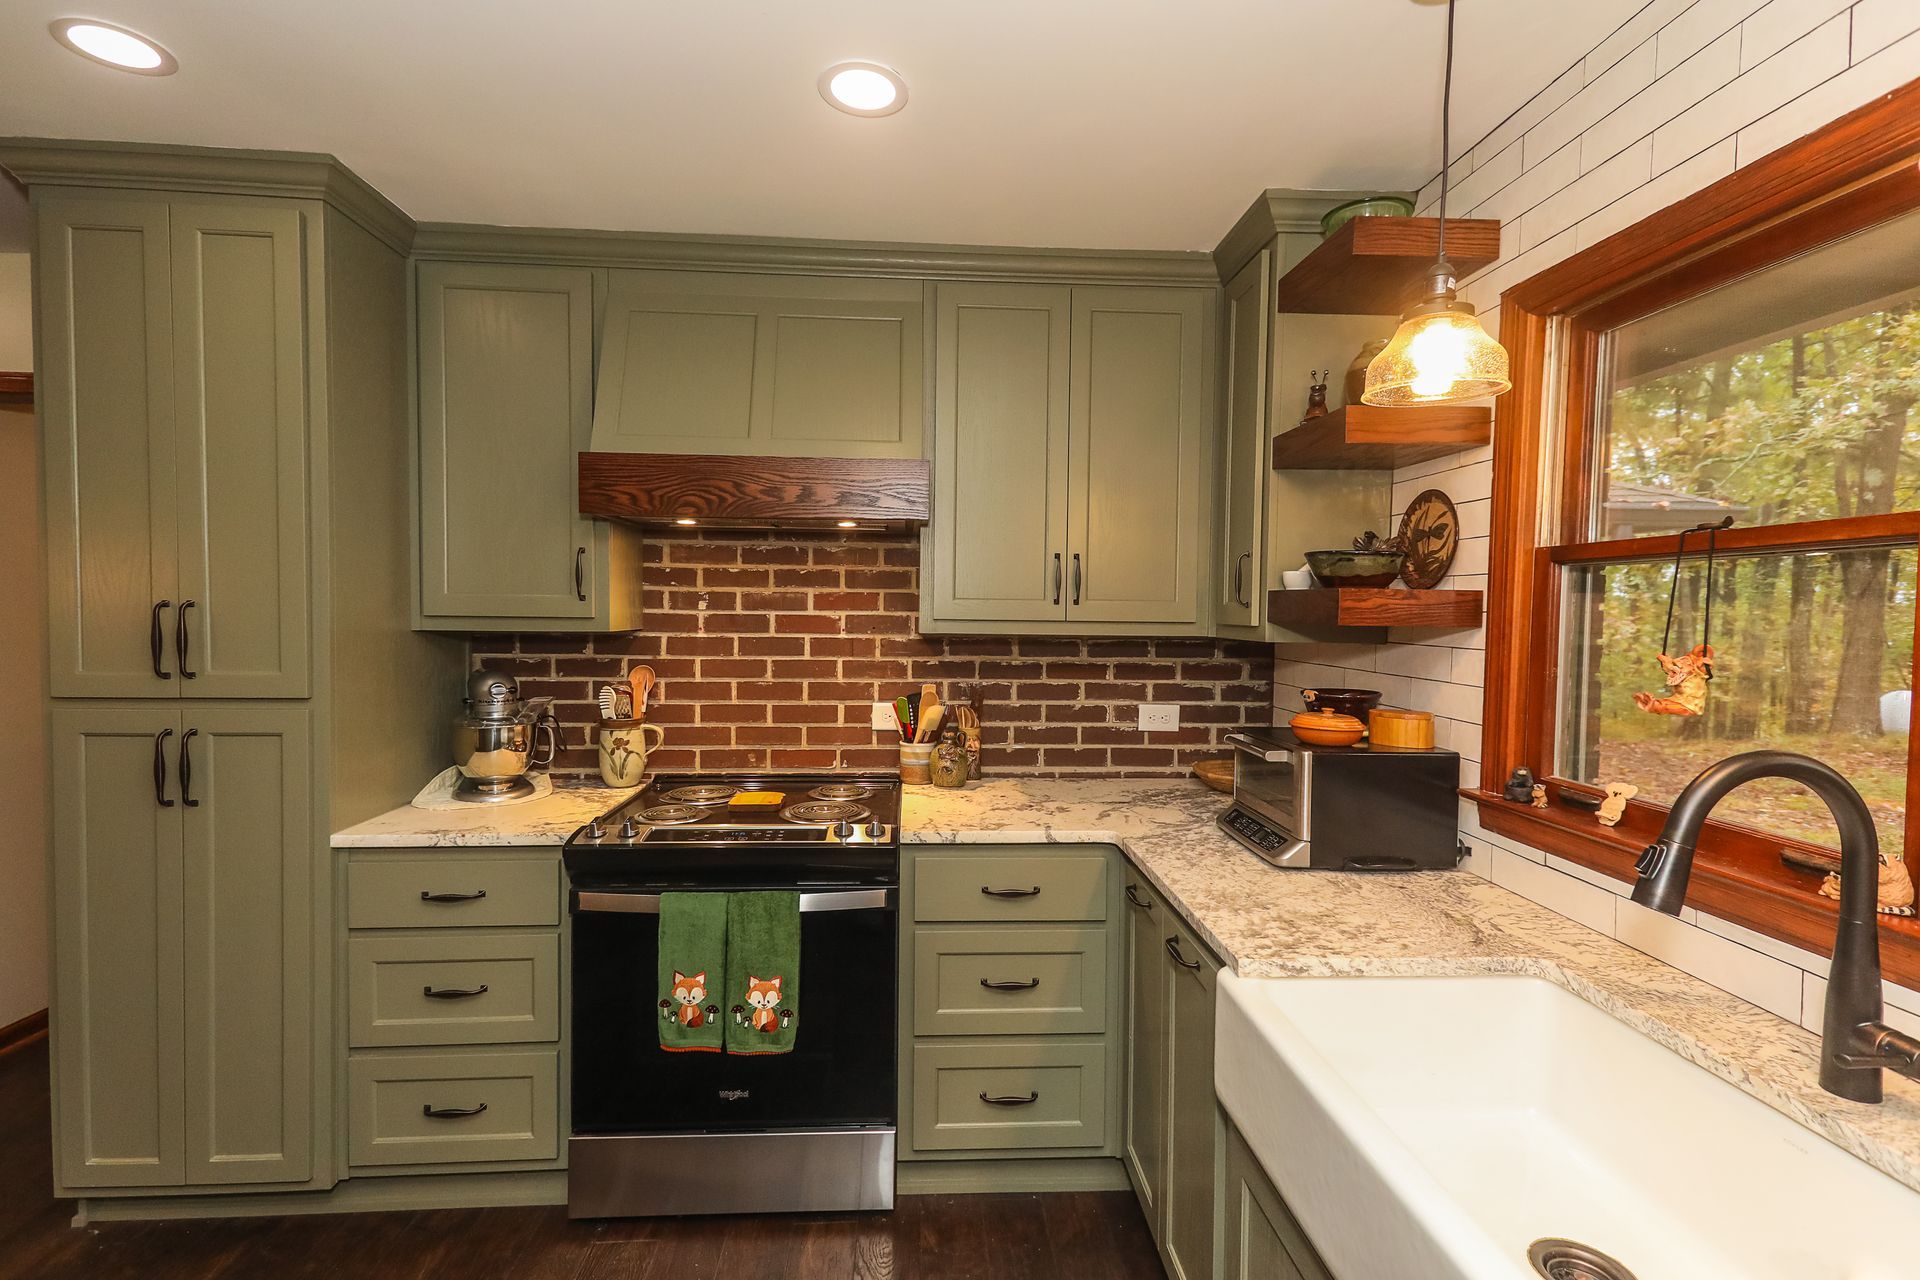
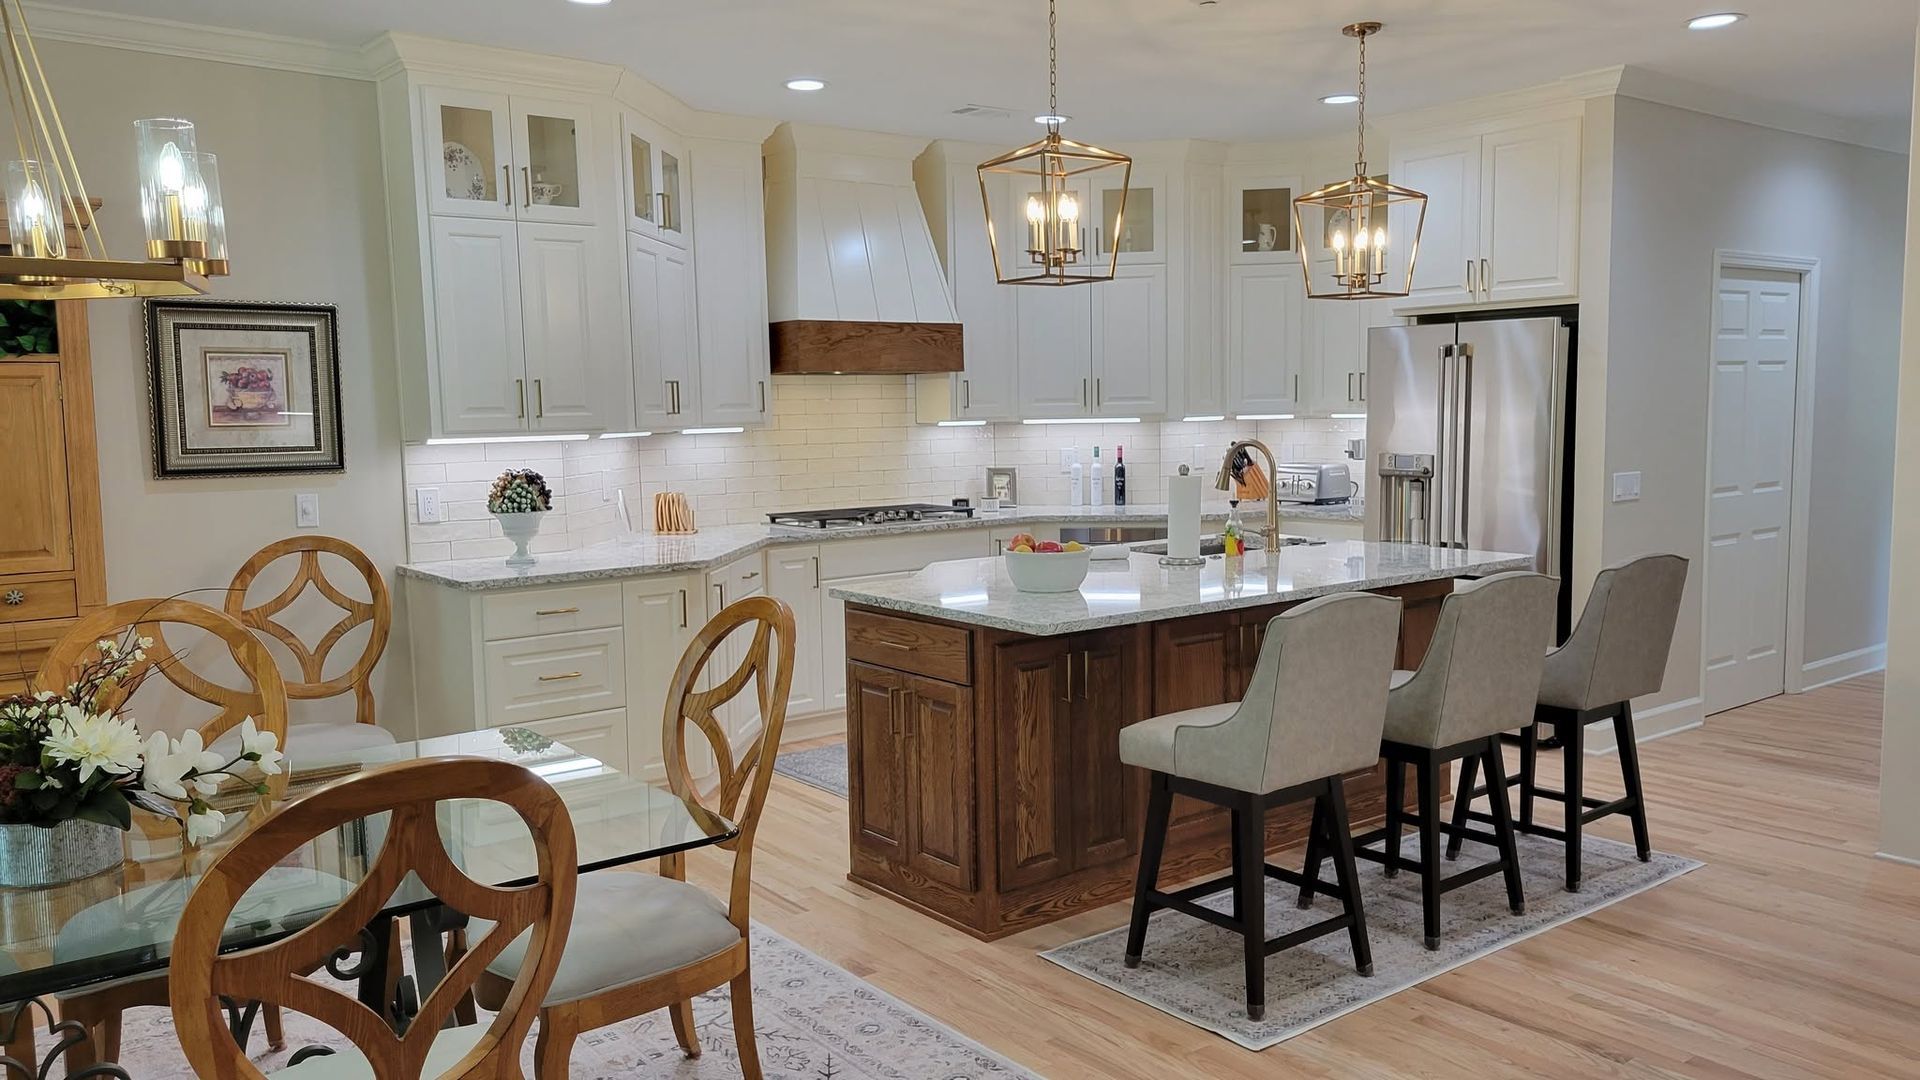
The biggest 2026 kitchen trend is warmth: colored cabinets, natural wood, layered lighting and smart storage. See how North Georgia homeowners are using it.
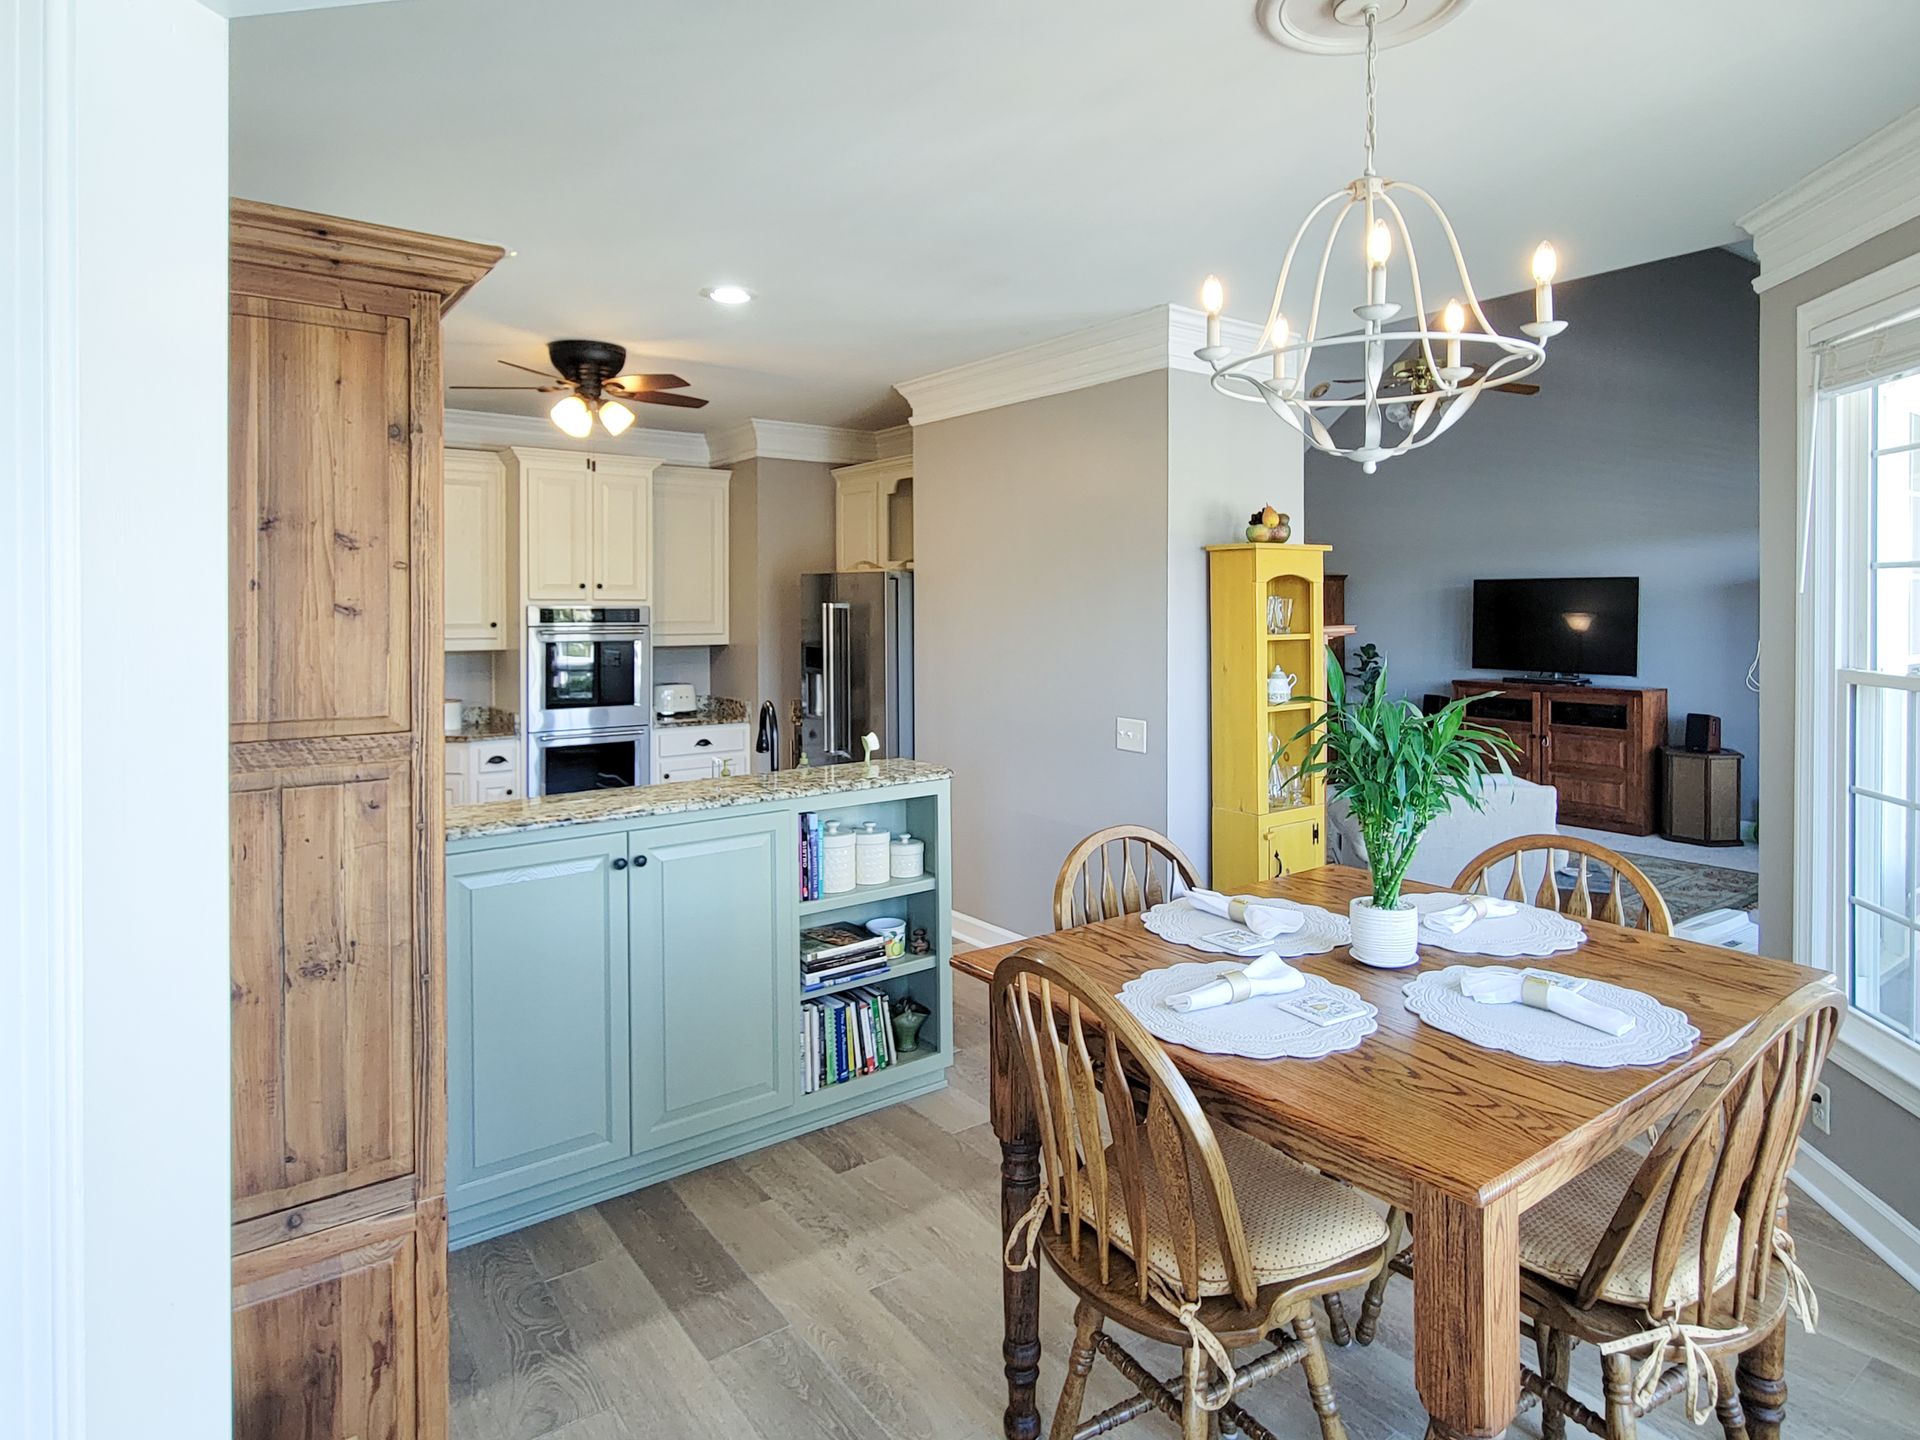
Design a home that works for grandparents, parents and kids. Multigenerational remodeling ideas for bedrooms, bathrooms, safety and flexible layouts in GA.
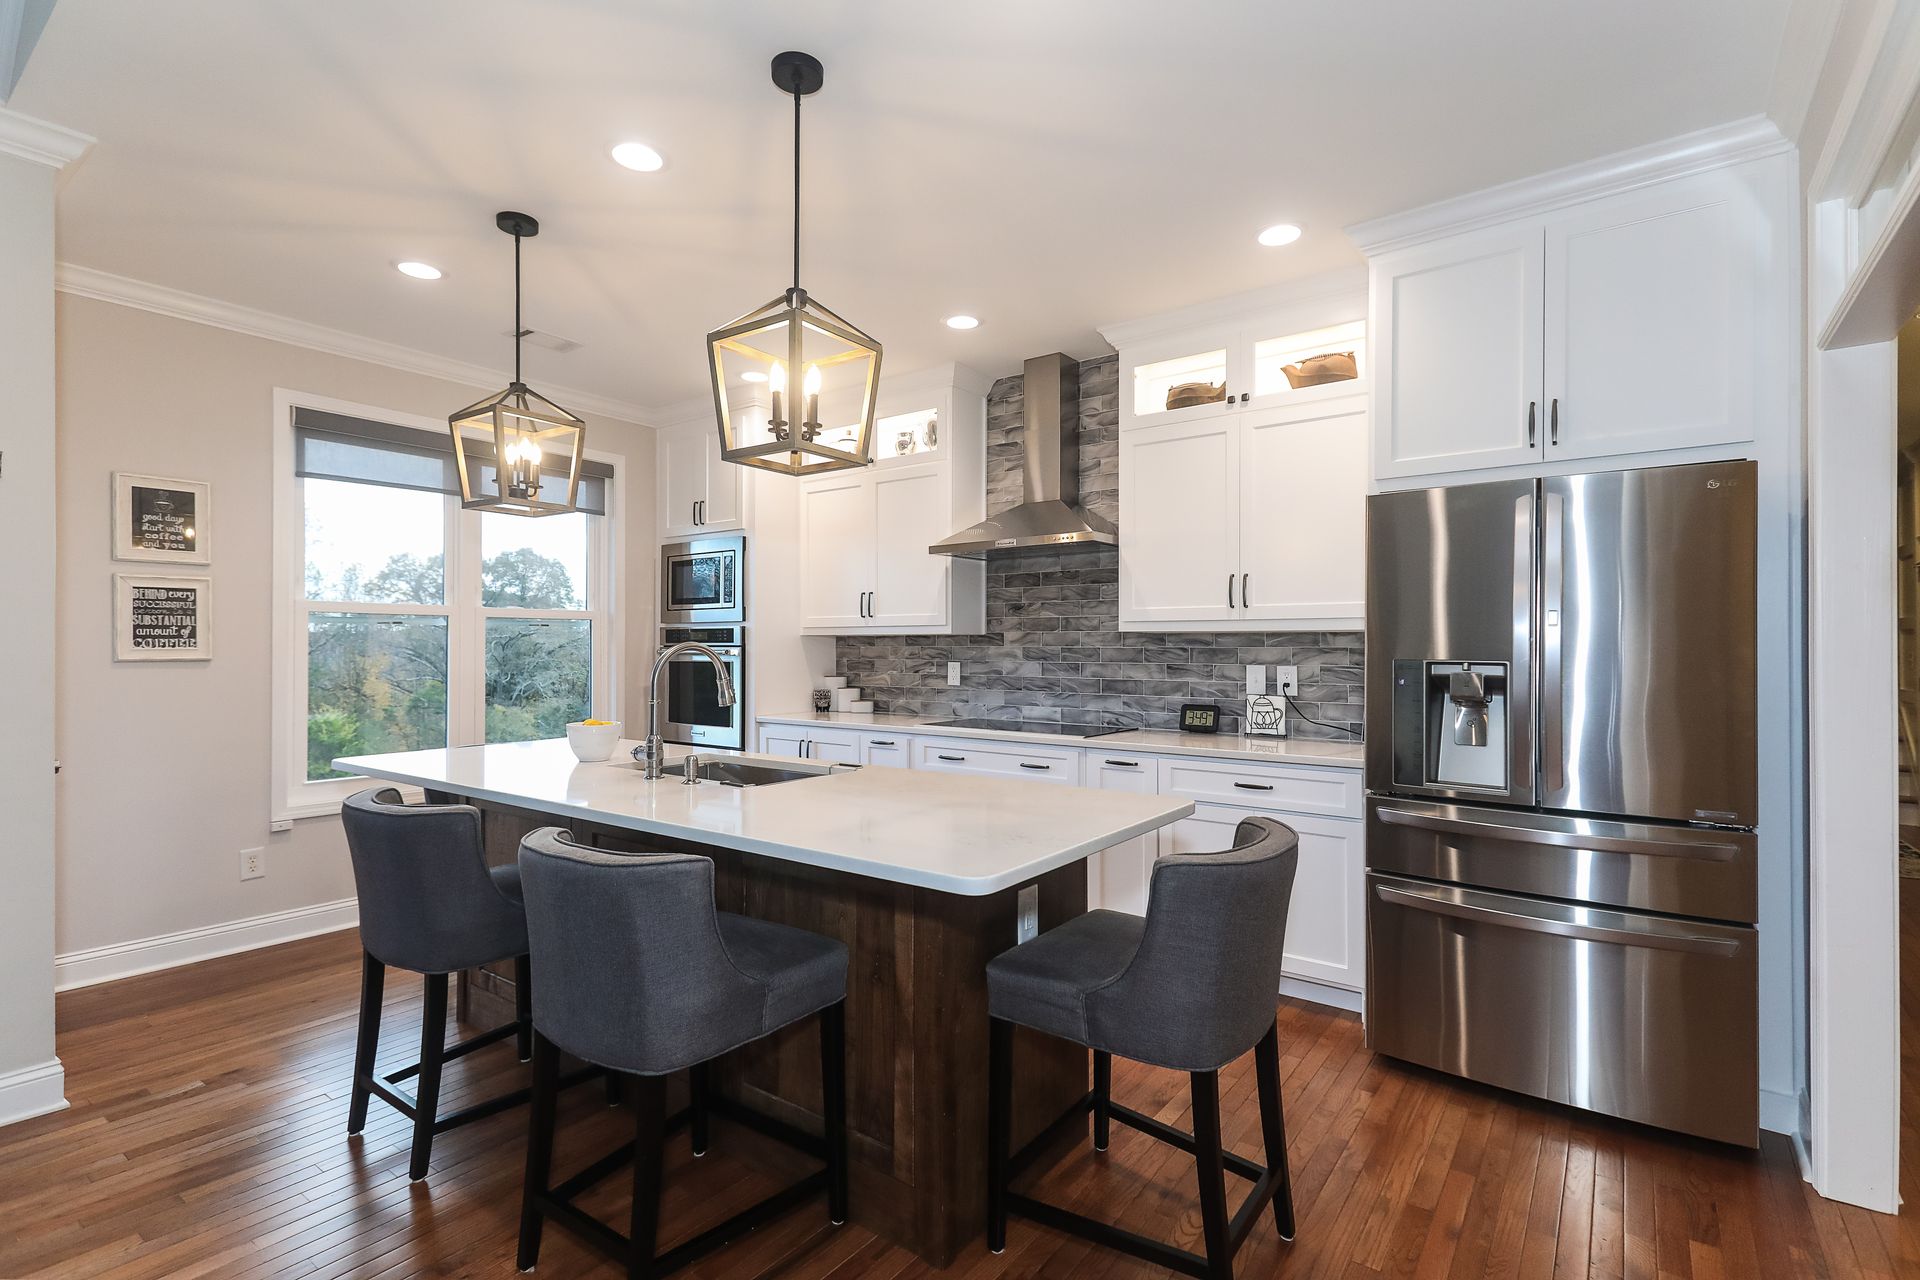
Add smart lighting, climate control, security and voice control during your remodel. Ideas for Gainesville, GA homeowners planning a kitchen or whole home update.
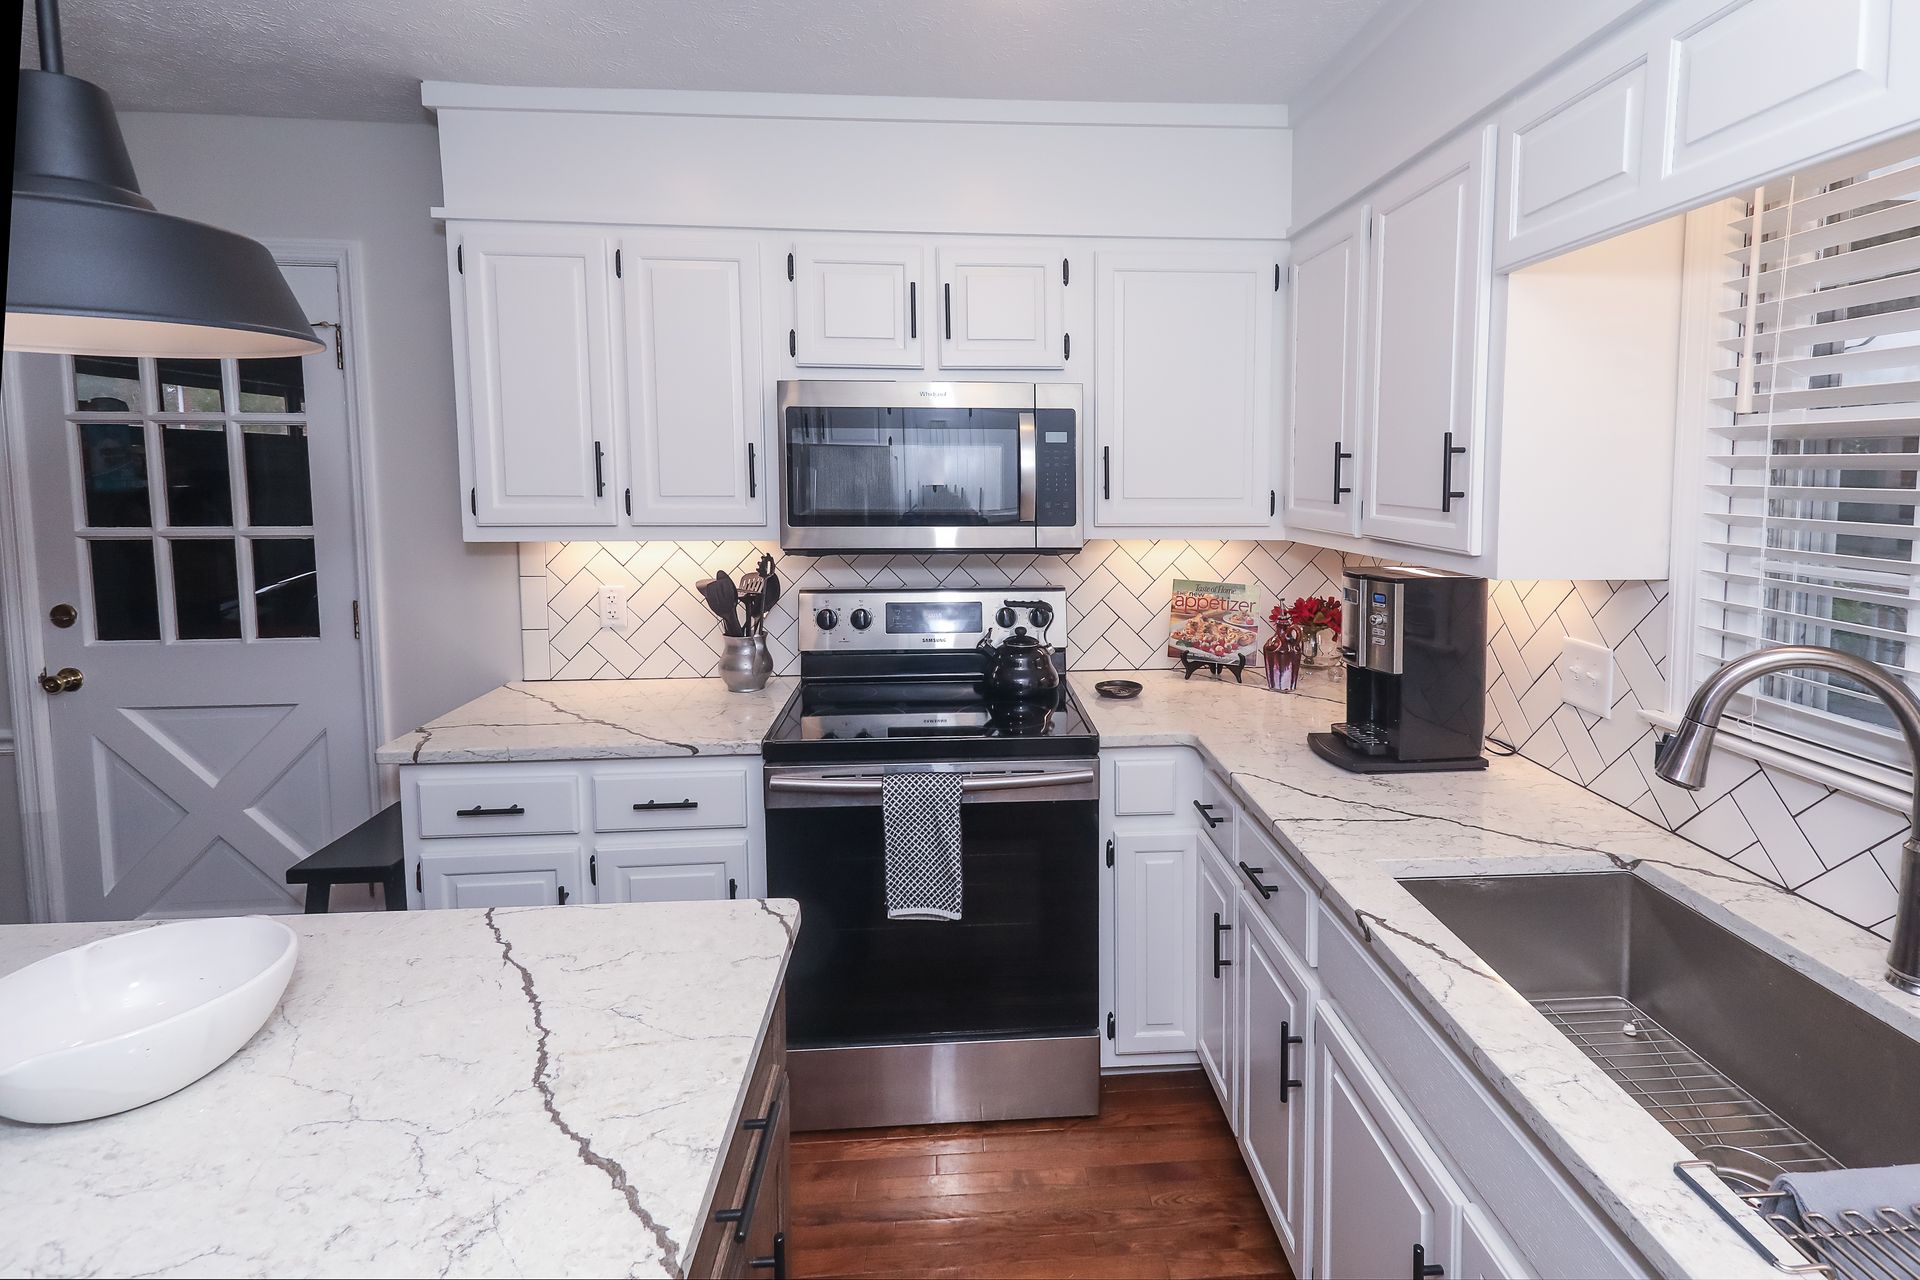
Avoid the most common home renovation mistakes. Planning, budgeting, permits and contractor communication tips from North Georgia design-build remodelers.
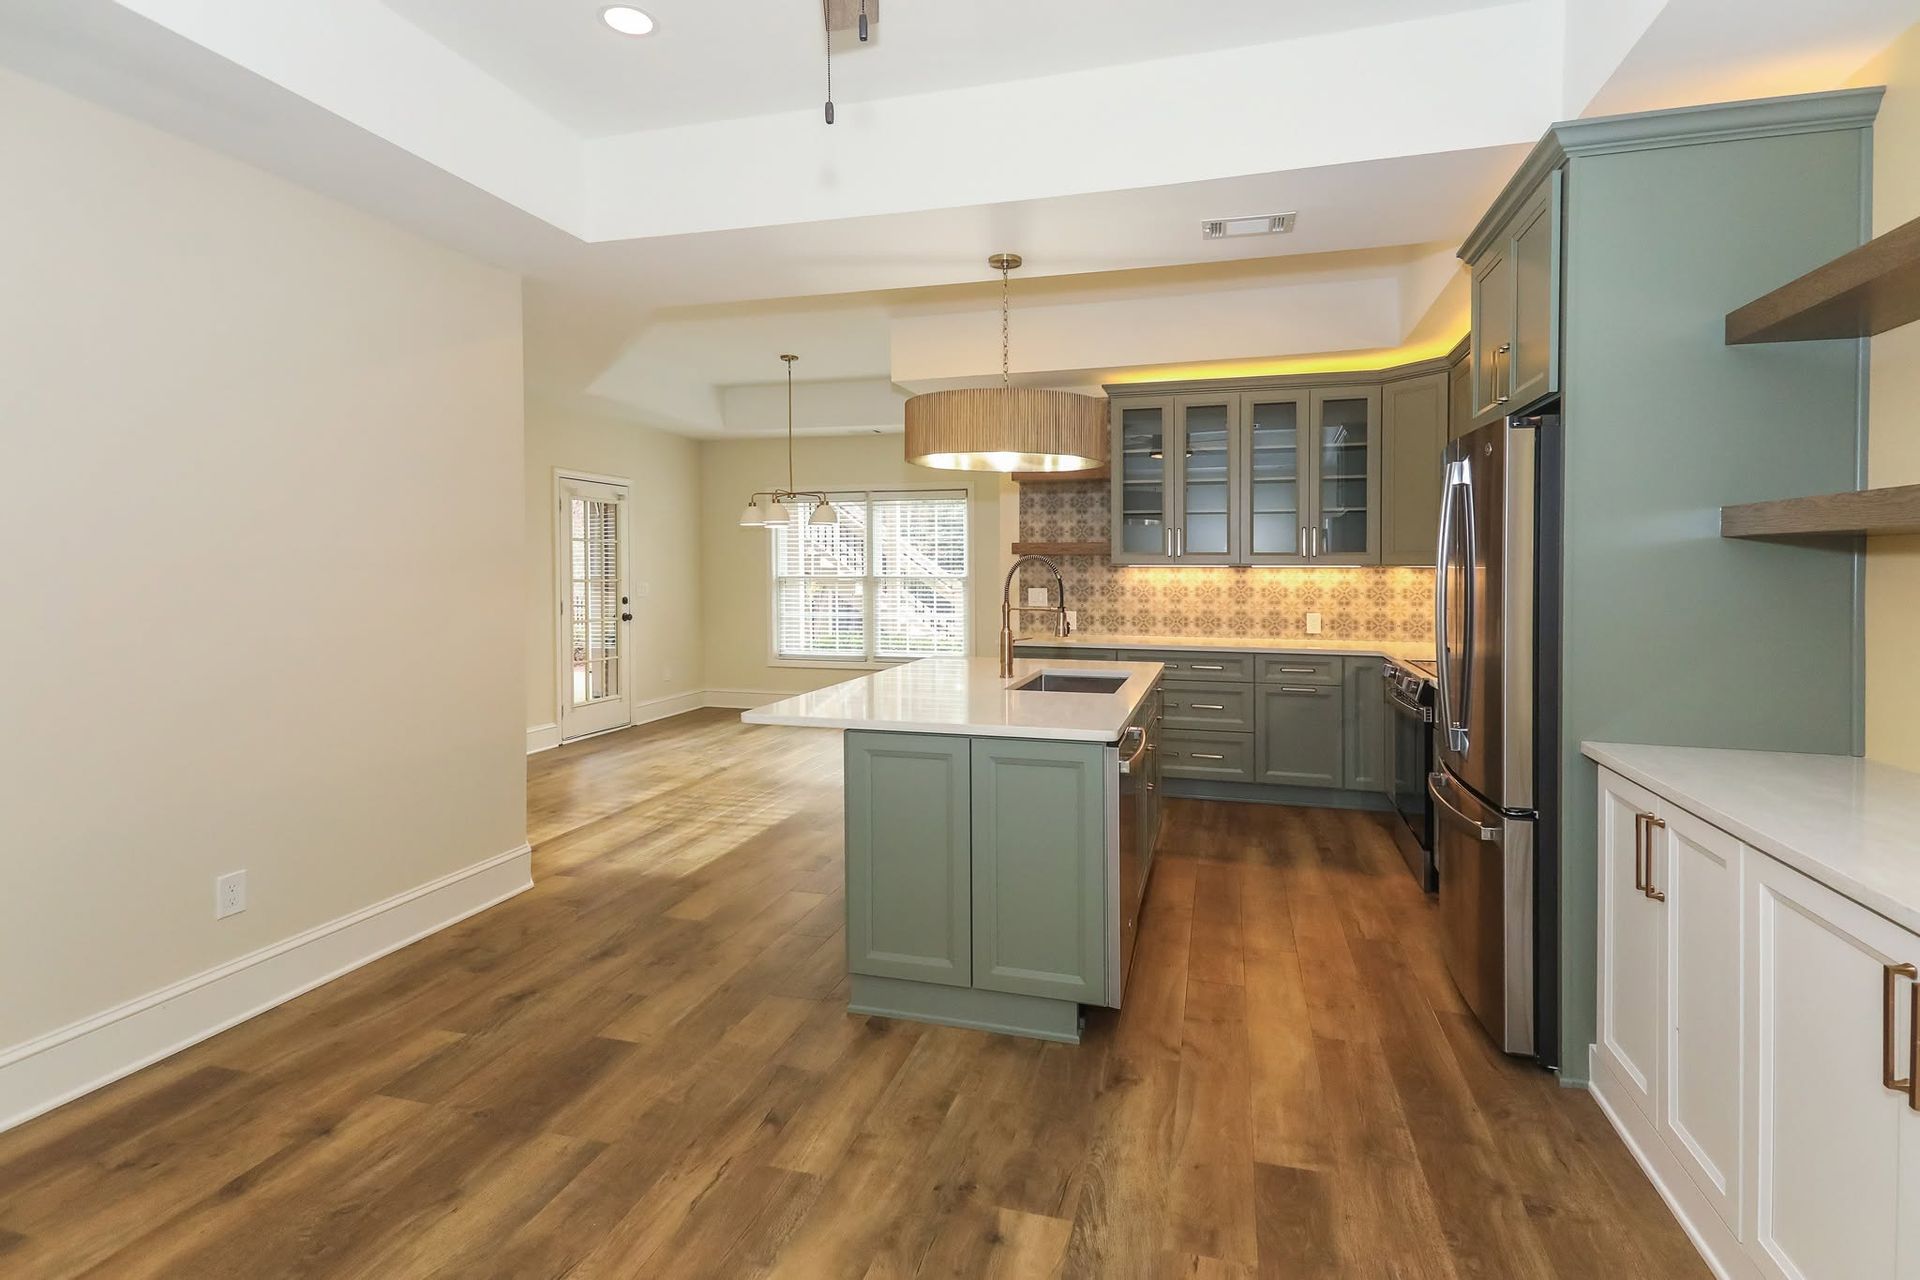
Turn your basement into a productive home office. Layout, lighting, ventilation, storage and comfort tips from Gainesville, GA design-build remodelers.
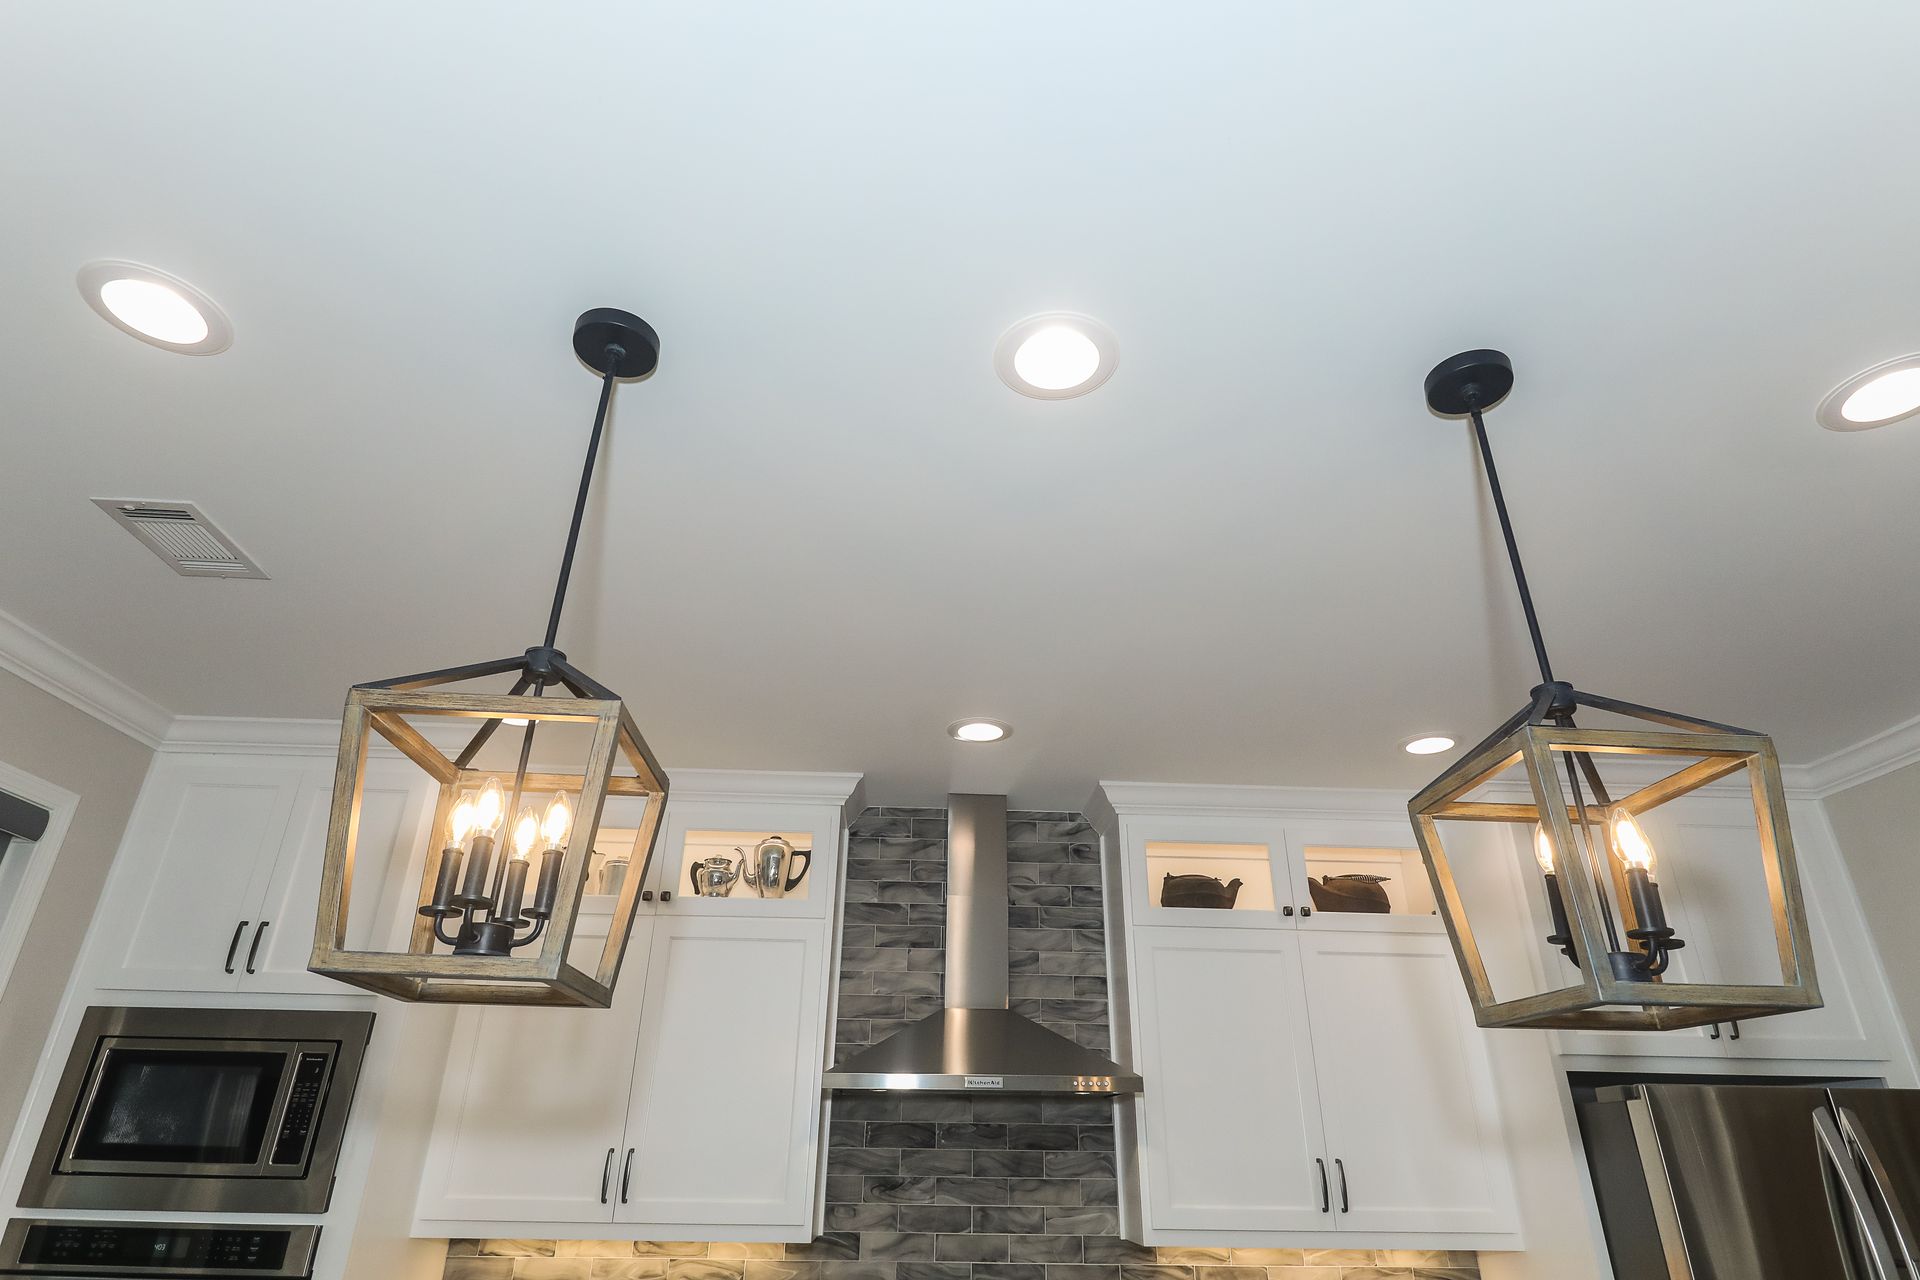
Learn how ambient, task and accent lighting transform kitchen design. Fixture tips, natural light ideas and color temperature guidance for your kitchen remodel.